Italy: Europe’s New Property-Portal Battleground

Long dominated by local champion Immobiliare.it, Italy’s online property market has become one of Europe’s most contested. Spanish-born idealista has built a formidable position since 2020 and its acquisition of Casa.it. In July 2026, CoStar Group added a new source of strategic capital by agreeing to acquire approximately 30% of agent-backed Wikicasa. Joreca assesses what this means for Europe’s fifth-largest online property-advertising market.
A large market with substantial headroom online
Italy combines scale with unusually attractive digital headroom. According to government sources (Agenzia delle Entrate), the country recorded roughly 720,000 residential transactions in 2024, returning it to growth and placing it among Europe’s largest housing markets, broadly behind France but ahead of Spain by transaction count. New-build supply remains a relatively small part of activity, so the market is still driven principally by existing homes.
Commercial real estate is also meaningful: investment volumes reached about €10 billion in 2024, with offices the largest segment at roughly €2.6 billion.
That physical scale translates into deep online inventory. Joreca counted more than 1.2 million residential properties advertised for sale or rent on 1 September 2026, across new and existing homes. The supply side is fragmented: more than 30,000 active estate agencies operate nationally, a pool comparable in order of magnitude with France or Germany.

This fragmentation matters. Portals can create value through reach, workflow tools, data and lead quality, but selling, onboarding and retaining thousands of small agencies remains operationally demanding.
Monetisation still trails the opportunity. Joreca estimates that total Italian portal revenues equal only 80–90% of Spain’s, even though Spain has around 16% fewer inhabitants and an economy approximately 23% smaller in nominal GDP terms than Italy. The main explanation is lower average recurring revenue per agency, reflecting historically measured pricing and a market in which multiple portals have remained credible. ARR has been rising, but the next competitive cycle may slow convergence with other major European markets.

Key Metrics
KPI | Residential | Source |
Residential transactions | 720k | Agenzia delle Entrate, FY 2024 |
Residential properties advertised online | 1.2m | Joreca, September 2026 |
Active online estate agencies | 30k | Joreca, September 2026 |
From local champion to contested duopoly
Italy’s first online shift was led by Casa.it, founded in 1996 and acquired by Australia’s REA Group in February 2007. Its subsequent loss of momentum opened space for Immobiliare.it, founded in 2005 by Carlo Giordano and Silvio Pagliani. The local challenger became the market leader by the end of the 2000s and still leads on traffic and active agency relationships. Its rise was supported by disciplined pricing: early packages were accessible and annual increases less aggressive than those seen in several other European portal markets.
Spanish-based idealista silently entered Italy in the middle of the 2000s with free or heavily promotional listing offers. Its decisive acceleration came in 2020. EQT agreed to acquire idealista on 10 September and Casa.it on 17 September, creating common ownership while retaining distinct brands. Casa.it brought a sizeable base of paying agencies; idealista brought technology, audience-building expertise and increasingly sophisticated monetisation. Today, Joreca estimates that idealista remains second, but the gap with Immobiliare.it in both traffic and agency penetration has narrowed to below 20%.
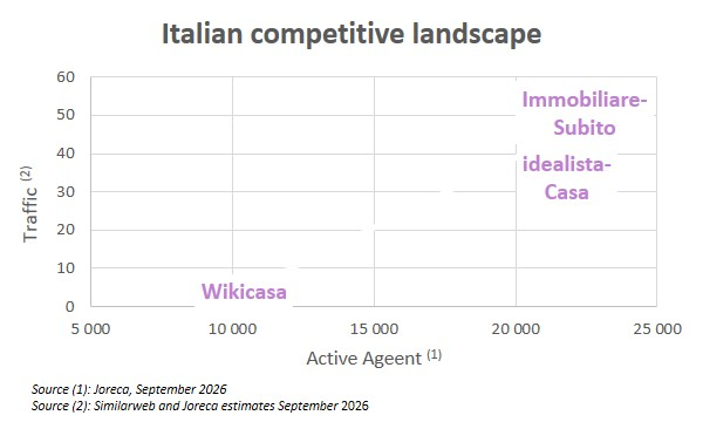
Wikicasa emerged as an agent-backed response to this duopoly. Launched in 2015, it assembled shareholders including Tecnocasa, Gabetti, RE/MAX Italy and Tempocasa—an approach reminiscent of agent-backed OnTheMarket in the UK and Bien’ici in France. The strategic aim was not simply to build a third portal, but to preserve negotiating leverage for agencies and constrain pricing by the leaders. Wikicasa established a credible inventory base, yet its audience and paying-customer scale remained materially below those of the top two.
The next 12 to 24 months could reset the market
CoStar’s 1 July 2026 agreement to take approximately 30% of Wikicasa changes the range of possible outcomes. CoStar can add capital, marketplace technology, Matterport capabilities and international distribution through LoopNet. A minority investment is not yet a full-scale assault; it is, however, a low-risk way for CoStar to learn the Italian market before deciding whether to invest much more aggressively.
Immobiliare.it has already moved on two fronts. In April 2026 it partnered with Subito, Italy’s leading horizontal re-commerce platform, extending professional listings into a channel with 2.8 million daily users and strong private-seller inventory. This matters in a country where owner-direct supply remains structurally important. Abroad, Immobiliare.it acquired Spain’s number-three portal Pisos.com from Vocento for €22.5 million in March 2025, an opportunity to pressure idealista in its home market while diversifying its own growth.
The unanswered question is idealista’s response. No comparably structural move has yet followed CoStar–Wikicasa or Immobiliare.it–Subito. It could intensify traffic investment, use Casa.it more aggressively, deepen agency software integration or pursue another acquisition. Whichever route it takes, competitive spending is likely to rise before market structure settles.
For agencies, that should preserve choice and restrain near-term ARR inflation; for portals, it raises the premium on product differentiation, demonstrable lead quality and disciplined customer economics. Italy is no longer merely a large market with room to digitise; it is becoming the European laboratory for how portal competition evolves when three well-capitalised models collide.
Disclaimer
This article was written using Joreca’s data, public information, and expert opinion. Under no circumstances does this article constitute a solicitation, offer, opinion, approval nor recommendation by Joreca, to buy or sell any company share, nor does it provide legal, tax, accounting or investment advice, nor services regarding the profitability or suitability of any security or investment.
Want to know more?Contact us at contact@joreca.com


